TL;DR
- This article works as a self-assessment: attempt the questions first, then check the explanations.
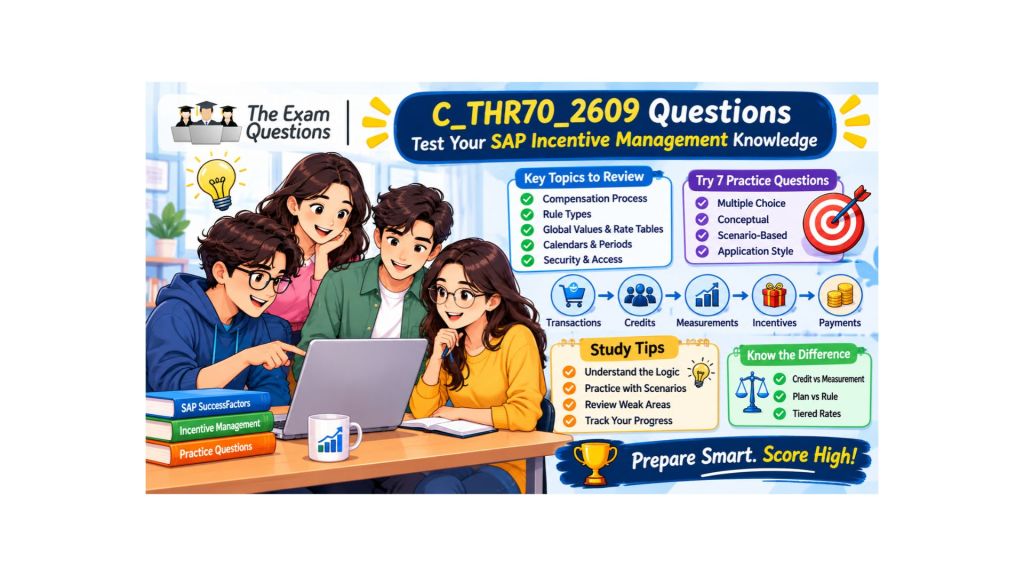
- You will revise five core Incentive Management ideas: the compensation process, rule types, global values and rate tables, calendars and periods, and security.
- Seven original practice questions mix multiple-choice, conceptual, scenario-based and application-style formats.
- A short scoring guide shows which topics to revisit. It does not predict your real exam result.
- Every question here is original practice material, not official or leaked SAP content.
Reading about a certification feels productive right up until someone asks you a direct question. Working through C_THR70_2609 Questions is one of the fastest ways to learn whether you actually understand SAP Incentive Management or only recognise its vocabulary. This guide is built as a self-check rather than a study manual, so grab a notepad, answer honestly, and treat every wrong answer as useful information.
Why Testing Your Knowledge Comes Before the Exam
Most candidates over-invest in reading and under-invest in retrieval. Research on learning consistently shows that trying to recall an answer strengthens memory more than rereading the same page. For a certification like C_THR70, which covers SAP SuccessFactors Incentive Management (formerly SAP Commissions), that matters because the subject is about connecting ideas. A payout is the end of a chain: data comes in, rules act on it, and money comes out. If one link is fuzzy, the whole chain is fuzzy.
Self-testing also exposes the gap between recognising and explaining. You may nod along when you see the phrase measurement rule, yet freeze when a scenario asks which rule type solves a specific problem. Finding that out at your desk costs nothing. Finding it out during the exam costs a lot more.
A quick word on shortcuts. You will see searches for C_THR70 Dumps, and it is worth being direct: memorised answer lists teach you nothing about configuring a plan, they may breach SAP’s certification terms, and they fall apart the moment a question is worded differently. Original practice questions, like the ones below, train the reasoning that scenario-based questions reward.
What Should You Understand About SAP Incentive Management?
SAP SuccessFactors Incentive Management is a solution for designing, calculating and administering variable pay, typically sales commissions and bonus plans. A consultant working with it is expected to understand the full process, not just one screen.
At a practical level, that process looks like this: organisations define who is paid (participants, positions and titles), what they are paid on (transactions such as orders or invoices), and how they are paid (plans built from rules, formulas and tables). The system then runs calculations for a defined period, produces earnings, and passes payment information onward.
If you learn better by watching, this video gives a useful walkthrough to pair with the questions below:
Quick reflection: Without looking anything up, can you describe in two sentences how a sales order ends up as a commission payment? If you hesitated, that is a good sign you are in the right place.
Five Concepts Worth Revising Before You Test Yourself
1. The end-to-end compensation process
Every question about calculations rests on one idea: transactions feed credits, credits feed measurements, measurements feed incentives, and incentives lead to deposits. Be able to say what each stage contributes and why the order matters.
2. Rule types and what each one does
Credit rules assign credit to participants from transactions. Measurement rules summarise credits or other data into a measurable value such as quota attainment. Incentive rules turn that measurement into earnings. Deposit rules prepare earnings for payment. Many scenario questions are really asking which of these four is the right tool.
3. Global values, variables and rate tables
Values that change rarely, or that should be maintained in one place, belong in a reusable structure rather than being typed repeatedly into formulas. Rate or lookup tables let a payout vary by tier without rewriting logic. Ask yourself why centralising a value reduces risk.
4. Calendars and periods
Calculations run against periods, and periods come from calendars. Understanding how a calendar is structured helps you reason about monthly, quarterly and annual plans and about why a transaction lands in a particular period.
5. Security, users and roles
Incentive data is sensitive. Know that access is controlled through users and roles, and be ready to reason about who should see, change or approve what.
When you are ready to compare your revision against the source, review the official certification information on SAP Training. Exam versions, delivery details and requirements change, so always confirm the current exam code, topic areas and scoring rules there rather than relying on any third-party article, including this one.
Seven Original Practice Questions
These are original learning exercises written for this article. They are not actual SAP exam questions, and they do not reproduce or predict official content. Try each one before scrolling to the answers. Write your answer down first; commit to it, then check.
Question 1 (Multiple choice)
A company wants to summarise each representative’s credited sales for a quarter into a single attainment figure. Which rule type is designed for this purpose?
A. Credit rule
B. Measurement rule
C. Incentive rule
D. Deposit rule
Question 2 (Conceptual)
Why is it generally better to store a value such as a standard commission percentage in a central, reusable location instead of typing it separately into several formulas?
A. It makes the calculation run faster in every case.
B. It removes the need for plans altogether.
C. It allows one change to update every place that uses the value, reducing errors.
D. It lets participants edit their own rates.
Question 3 (Short scenario)
An order is booked on the last day of a quarter, but the sales team reports that it appears in the following quarter’s results. Which area should you investigate first?
A. The participant’s job title only
B. The calendar and period setup, along with the transaction’s date
C. The colour theme of the user interface
D. The number of users with administrator access
Question 4 (Application, calculation)
A plan pays 5% on sales up to quota and 8% on sales above quota. A representative has a quota of 100,000 and closes 120,000 in sales. Assuming the rate applies only to the portion of sales in each tier, what is the incentive?
A. 6,000
B. 6,600
C. 9,600
D. 5,000
Question 5 (Conceptual)
In your own words, explain the difference between a credit and a measurement. Use a one-sentence example for each.
Question 6 (Short scenario)
A regional sales manager should be able to view the compensation results of their own team but must not be able to edit plan rules. What is the most appropriate approach?
A. Share one administrator login with all managers.
B. Give every manager full access, then ask them not to change anything.
C. Assign a role with permissions limited to viewing the relevant data.
D. Export all results to a spreadsheet and email it weekly instead of using the system.
Question 7 (Application, troubleshooting)
A representative’s payout is lower than expected. Which approach is most sensible?
A. Increase the payout manually without investigating.
B. Follow the chain from the original transactions through credits, measurements, incentives and deposits to find where the value changed.
C. Delete the plan and rebuild it from scratch.
D. Assume the participant’s report is wrong and close the query.
Pause here. Before reading on, mark your answers. If you are unsure, note whether the uncertainty is about a concept (you did not know it) or about a detail (you knew it but misread the question). That distinction shapes how you should study next.
Answers and Explanations
Answer 1: B, Measurement rule
A measurement rule aggregates data, such as credits, into a value you can evaluate, for example quarterly attainment. A credit rule (A) decides who receives credit for a transaction, not how credits are summarised. An incentive rule (C) converts a measurement into earnings, so it comes after the summary you are asked about. A deposit rule (D) prepares earnings for payment and is the final step.
Answer 2: C, One change updates every use and reduces errors
Centralised values support consistency and maintainability. Option A overstates the case, since speed is not the main benefit. Option B is incorrect because plans are still needed to define how pay is calculated. Option D confuses reusability with participant access, which is controlled separately through security.
Answer 3: B, The calendar, period setup and transaction date
Results are calculated by period, so the date on the transaction and the period boundaries are the logical first check. A job title (A) affects who receives credit, not which period a transaction falls into. Interface appearance (C) has no bearing on calculations. Administrator access counts (D) are a security concern, not a period concern.
Answer 4: B, 6,600
The first 100,000 earns 5%, which is 5,000. The extra 20,000 earns 8%, which is 1,600. Together that is 6,600. Option A, 6,000, wrongly applies 5% to all 120,000. Option C, 9,600, wrongly applies 8% to everything. Option D, 5,000, ignores the above-quota portion. If you missed this one, practise reading tier descriptions carefully and noting whether a rate applies to the whole amount or only to the slice.
Answer 5: Model answer
A credit records that a participant receives recognition for a specific transaction. For example, a representative is credited with a 10,000 order. A measurement combines credits (and sometimes other data) into a figure used for evaluation. For example, the total credits for the quarter become 120% quota attainment. If your explanation separates “per transaction” from “summarised result”, you have the right idea.
Answer 6: C, A role limited to viewing the relevant data
Roles exist so that people receive only the access their job requires. Shared logins (A) destroy accountability and are poor security practice. Giving full access and relying on goodwill (B) does not protect the data. Manual exports (D) create extra risk and bypass the system’s access controls.
Answer 7: B, Trace the chain from transactions to deposits
A structured trace finds the real cause, whether that is a missing credit, a wrong rate or a period issue. Manual adjustment (A) hides the underlying problem and may repeat it next period. Rebuilding everything (C) is disproportionate and risky. Dismissing the report (D) is neither professional nor accurate.
How Well Did You Perform?
Use this guide to decide what to do next. It is a study aid only and does not predict, estimate or guarantee any real examination result.
Six or seven correct: Your fundamentals look solid. Move on to harder C_THR70_2609 Scenario Questions that combine several concepts, and practise explaining your reasoning aloud.
Four or five correct: You have a good base with a few soft spots. Look at which rule or concept your wrong answers share, then revisit that topic in the official learning materials before retrying.
Three or fewer correct: That is perfectly normal at the start. Return to the end-to-end process first, make sure you can describe each stage in plain words, and then retest yourself in a few days.
Also check how you got answers right. A lucky guess is not knowledge, so count only the answers you could defend with a reason.
Five Last-Minute Revision Recommendations
- Redraw the process from memory. Sketch transactions, credits, measurements, incentives and deposits without notes, then compare.
- Rewrite your wrong answers. For each miss, write one sentence explaining why the right answer is right and why yours was not.
- Practise reading scenarios slowly. Underline the exact problem being asked about before looking at the options.
- Verify exam details at the source. Check the current exam code, topics, duration and scoring on SAP’s own pages, since details can change between versions.
- Rest properly the night before. Sleep helps recall more than another hour of cramming.
Final Thoughts
Self-testing turns passive reading into honest feedback, and honest feedback is what makes preparation efficient. Retake these questions after a few days, write your own scenarios from your project or study experience, and keep checking your understanding against SAP’s official materials, then continue your practice with more C_THR70 Questions from The Exam Questions.


Leave a Reply